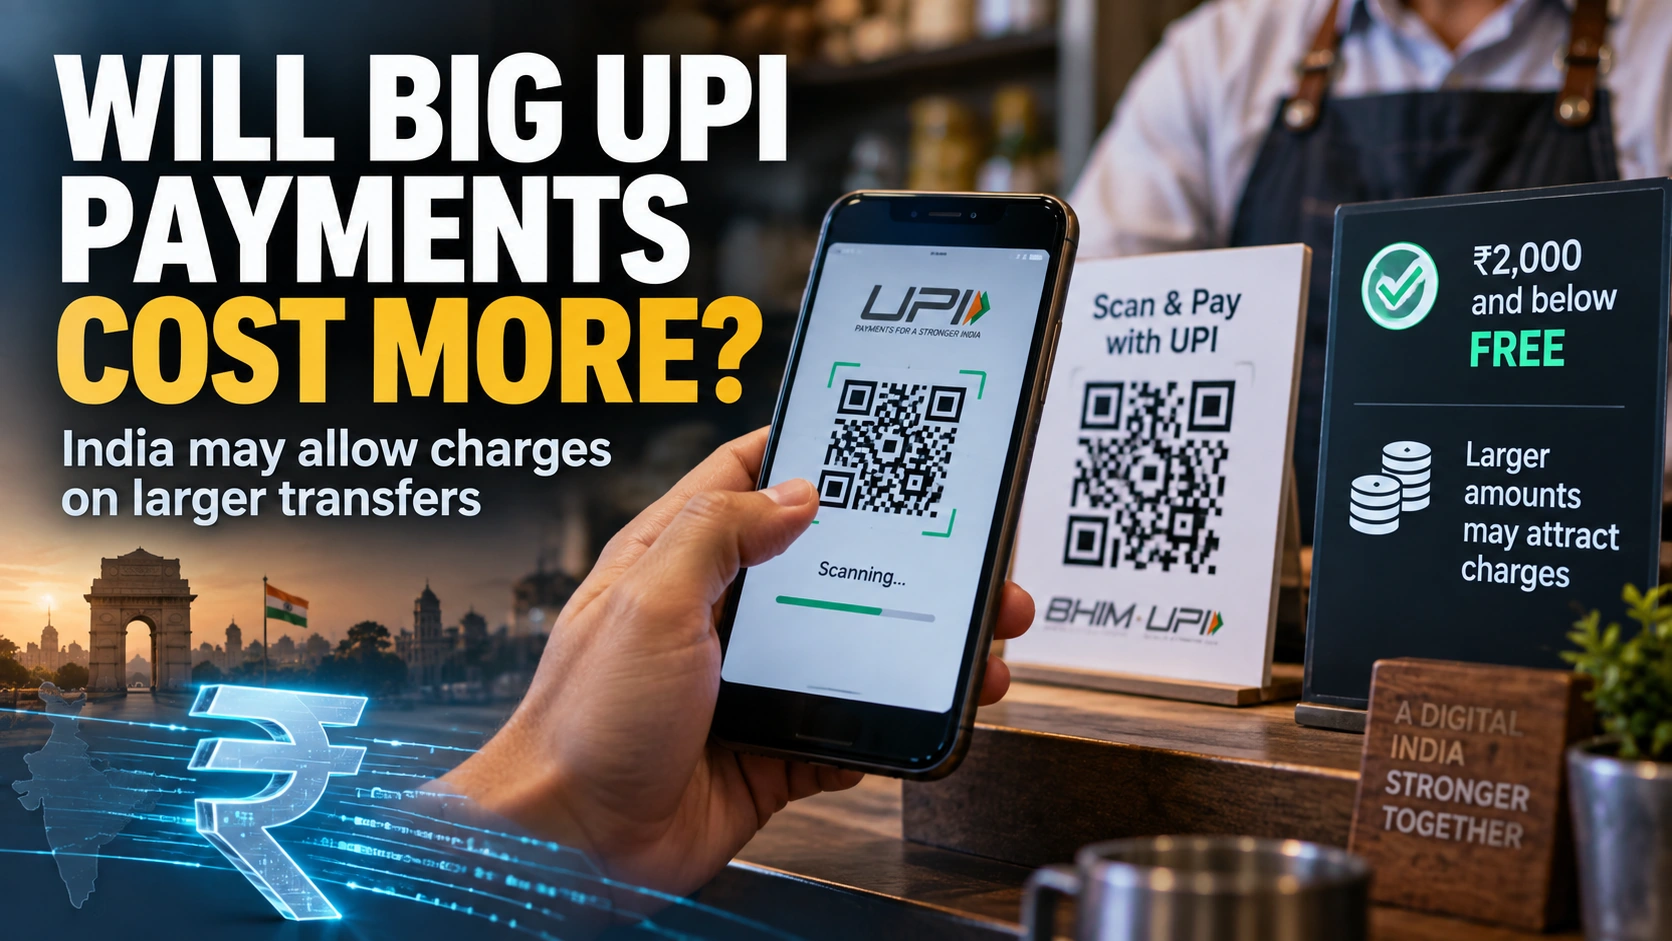
India has opened the door to a potentially major shift in digital payments policy by allowing a framework under which larger UPI transfers could face charges in the future.
What the new rule says
The latest regulatory change keeps UPI payments up to ₹2,000 free of bank charges. That is the clear protection built into the system. But the bigger talking point is what comes next: for transfers above that threshold, the previous blanket ban on charging has been relaxed, meaning the policy space now exists for fees to be introduced later.
Why this is such a big conversation
UPI has become central to daily commerce in India, from small shop transactions to peer-to-peer transfers. Any suggestion that the cost structure may change naturally raises anxiety among consumers, merchants and banks. Even without an immediate fee announcement, the possibility alone is enough to trigger debate.
What it could mean for users
For everyday low-value payments, nothing changes for now. The uncertainty lies with larger transactions. If charges are eventually imposed, users may rethink how they split payments or which rails they use. Merchants and financial firms will also watch closely because pricing can influence usage behaviour at scale.
Why the government is balancing carefully
India wants to keep digital payments accessible while also dealing with the economics of operating a massive payment system. That creates a tension between public adoption and commercial sustainability. The current change looks like an attempt to preserve free small-ticket usage while keeping policy flexibility for higher-value transfers.
Bottom line
UPI remains free for smaller transactions, but India has clearly signalled that the debate over who pays for the system — and when — is no longer off the table.
Source: Reuters